



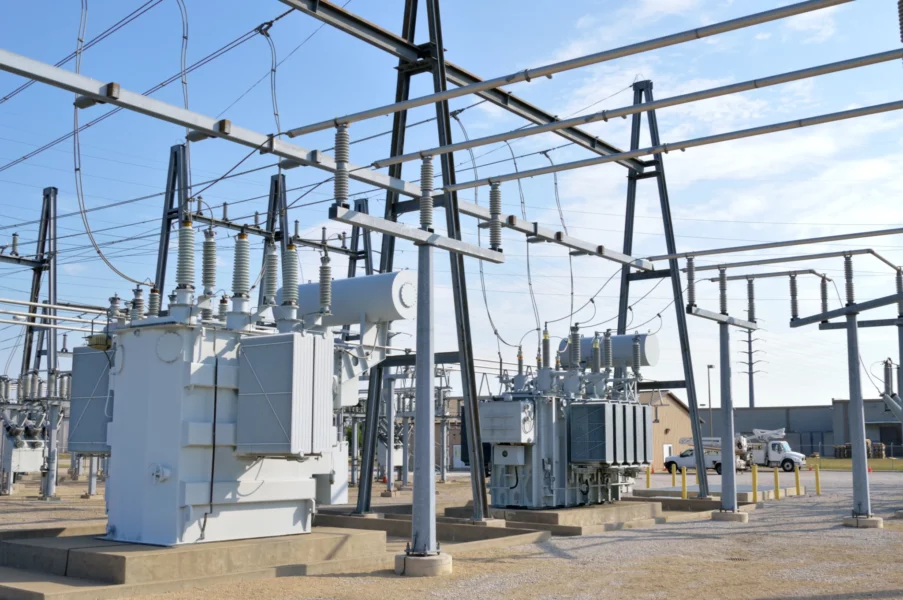

On-site generation has emerged as the data center industry’s primary answer to a genuine infrastructure problem. Interconnection queues now run three to seven years in many markets. Grid capacity is most constrained in exactly the regions where demand is surging fastest. And operators constructing facilities measured in hundreds of megawatts cannot afford to wait for traditional utility timelines to catch up.
So, they are doing what any rational business would do: generating their own power. More than 60% of data centers are actively exploring on-site generation. By 2030, over 35 GW of data center load is projected to come from self-generation. That number that would have been almost unthinkable just five years ago.
On-site generation addresses a real constraint. But in doing so, it creates several new ones for the operators who build it, for utilities left on the sidelines of one of the fastest-growing load categories in modern history and for the millions of ratepayers whose bills will feel the consequences of a progressively fragmented grid.
There is a better way forward. It requires utilities and large customers to stop viewing each other as obstacles and start working together as partners in financing and developing the infrastructure the grid genuinely needs.
What On-Site Generation Gets Right
The data center industry has identified a genuine and pressing challenge. Time-to-power is a real and significant constraint. While a data center can be designed and constructed in 18 to 24 months, securing power through conventional utility interconnection takes an average of three to seven years, with timelines stretching even longer in heavily congested regions such as PJM.
On-site generation directly addresses that gap. Operators who own their generation assets control their own fuel supply, dispatch decisions and maintenance schedules without exposure to interconnection queues or utility timelines. For facilities where a single minute of downtime can represent millions of dollars in losses, that level of operational control is not a discretionary advantage. It is a core business requirement.
This shift is structural, not cyclical. The move toward behind-the-meter generation reflects a fundamental mismatch between the pace of data center development and the pace of grid infrastructure and that mismatch is not resolving quickly.
What on-site generation does not do, however, is eliminate the underlying energy challenge. It relocates cost, risk and operational complexity away from systems purpose-built to manage them efficiently, and onto corporate balance sheets that were not designed to carry them. Compressing time-to-power is a meaningful achievement. Treating it as a complete solution is where the analysis deserves greater scrutiny.
Related Services
Understanding the Full Picture of On-Site Generation
On-site generation offers real advantages but realizing them requires a clear-eyed view of the full capital commitment involved. Operators building generation assets take on responsibilities that extend well beyond the initial equipment purchase.
Those commitments include:
- Redundancy and reliability infrastructure: Unlike grid-connected facilities, which can draw on a utility’s broader system during maintenance or outages, on-site operators must ensure backup capacity is built into the portfolio itself. Every planned maintenance window requires a parallel asset on standby which is a structural cost that grid-connected operators share across a much larger system.
- Power quality systems: Flywheels, batteries, synchronous condensers, power electronics and sophisticated control systems are delivered as shared services by the grid. Off-grid operators own, staff, and maintain these individually, adding both capital and operational complexity.
- Fuel supply and logistics: Continuously operating assets require long-term fuel contracts and supply chain management, with limited flexibility to adjust when market conditions shift.
- Specialized operational capabilities: Managing on-site generation requires engineering expertise that most data center operators are building for the first time whether developed internally or acquired through the market.
- Financing costs: All of this is funded at corporate borrowing rates which, even for investment-grade technology companies, are meaningfully higher than the regulated cost of capital available to utilities.
From an operational standpoint, achieving grid-equivalent reliability off-grid requires meaningful capacity overbuilds. Without neighboring assets to draw from, operating reserves must be physically owned rather than called from the broader system. The result is a generation portfolio that demands more capital and carries less flexibility than a grid-connected alternative.
None of this makes on-site generation the wrong choice, but it does make a complete accounting essential before committing.
Shared Stakes, Shared Opportunity
The decisions large operators make about how they power their facilities extend well beyond their own balance sheets. They shape the cost structure of the grid that millions of other customers depend on every day.
When large industrial customers build behind the meter, they typically retain a grid connection for backup and emergency service, continuing to benefit from shared infrastructure. These services are financed by the metered load connected to the grid. If large loads draw primary power from behind the meter assets, their energy draw from the utility doesn’t adequately compensate for these services, so does their contribution to the fixed costs of maintaining the system. Those costs are then carried by a smaller pool of residential customers, small businesses and fully grid-dependent ratepayers.
This is not an unsolvable problem. It is an invitation to think more carefully about how the costs and benefits of a modern grid are structured and shared. As the data center industry grows, it has a genuine opportunity to be a constructive force in that conversation rather than a complicating factor within it.
The scale of data center growth creates real risk if left uncoordinated, but it also represents real leverage. Operators who engage proactively with utilities and regulators on cost allocation and grid planning can help shape frameworks that are intended to support more durable and broadly balanced outcomes.
The question is not whether large customers should pursue their energy interests. They should and they will. The more important question is whether they pursue those interests in ways that strengthen the broader system or quietly erode it.
What a Collaborative Model Looks Like
The path forward is not about forcing data center operators back into three-to-seven-year interconnection queues. It is about designing a structure where utilities and large customers collaborate to develop generation infrastructure that serves both parties without either bearing the full cost and risk alone. Fixed mindsets and siloed approaches will never serve a world in flux. The opportunity lies in asking better questions and building outcomes that benefit the broader system.
The core mechanism is straightforward. When a large customer requests service, the utility evaluates whether that load can be served more cost-effectively, or more quickly, through a co-located distributed energy resource: a gas turbine, battery storage system or solar installation, rather than, or alongside, a conventional grid interconnection. The utility finances and constructs that asset using its lower cost of capital and infrastructure expertise. The asset enters the rate base. The customer pays it through rates across the asset’s useful life, rather than carrying it on their balance sheet upfront.
The customer maintains a grid connection for redundancy and backup. The interconnection request is smaller and the queue position more manageable. The utility earns its regulated return. And the generation asset, rather than sitting on a corporate balance sheet, providing benefit only to its owner, becomes part of the shared system, available to contribute to grid support functions, subject to system design and operating requirements.
This model succeeds because it plays to each party’s structural strengths. Utilities are built to finance large capital assets at regulated cost, construct and operate power systems and manage long-duration infrastructure risk. Data center operators are built to run computing infrastructure at scale. The collaborative model lets each do what they do best and allows the market to achieve outcomes neither party can reach independently.
The financial case is not marginal. When modeled for equivalent assets, the utility-financed approach may show a material net present value advantage under certain assumptions. The difference in cost of capital alone, sustained over a multi-decade asset life, may materially influence investment decisions in some circumstances.
The Opportunities Ahead
The data center industry’s energy challenge is significant. It is also solvable. The grid alone cannot meet the pace and scale of demand growth. On-site generation alone cannot bear the full weight of the capital and operational complexity involved. But a model that brings utilities and large customers together can do what neither can accomplish independently.
That model already has a clear shape. When utilities and large customers collaborate on the financing and development of distributed energy resources. The model may offer benefits such as faster time-to-power and lower lifecycle generation costs in certain applications.
The energy transition is one of the most consequential infrastructure challenges of our time. It is also one of the most significant partnership opportunities. The pressures it creates on the grid are real, but so are the conditions it establishes for new kinds of collaboration: ones that are more adaptive, more efficient and more equitable than the models that came before.
The data center industry has already demonstrated its capacity to move quickly, invest boldly and solve problems at scale. Bringing that same ambition to grid partnership, rather than grid separation, may help position the industry for longer-term competitive and societal benefits.
The choice is not between building power and buying it. It is between going it alone and helping to build the energy system the future actually requires. That second path is harder to start and far more valuable to finish.

Next Steps: TRC Can Help
TRC helps utilities and large energy users navigate the complexities of a rapidly evolving energy landscape. By combining deep power system expertise with strategic planning, regulatory insight and technology integration, we help clients address growing demand from data centers, industrial facilities and electrification initiatives.
From interconnection studies and engineering design to stakeholder engagement and rate impact analysis, TRC delivers integrated solutions that accelerate time-to-power, strengthen grid reliability and create long-term value for utilities, customers and the communities they serve.
